R&D Tax Credits for Additive Manufacturing

What is Additive Manufacturing?
Additive manufacturing is more commonly known as 3D printing, and it builds a part layer by layer from a digital file, adding material where needed. Traditional manufacturing often works in a different way, cutting, drilling, or forming a part out of a large block of material to produce the final product.
The technology splits into two broad material categories:
1) Polymer printing: uses materials like plastics, resins, and composites in a wide range of applications, including rapid prototyping, dental aligners, and production parts for consumer products.
2) Metal printing: uses materials like titanium, aluminum, stainless steel, and nickel-based superalloys, generally in applications in aerospace, defense, and medical implants, where strength, weight, and precision are all concurrently important.
The companies doing this kind of work generally fall into two groups:
1) Pure-play additive manufacturing companies, such as machine builders, material developers, and print service bureaus whose entire business is printing parts for other companies.
2) Companies that use more “conventional equipment” alongside additive printing to solve a specific engineering problem such as traditional manufacturers, aerospace primes, automative OEMs, or medical device makers.
What the R&D Tax Credit is, and Why Additive Manufacturers Can Qualify
The federal research credit rewards companies for resolving genuine technical uncertainty through testing, regardless of the industry in which the uncertainty and research occurs, and no dedicated research and development department is needed in order to qualify.
Many additive manufacturing companies perform research and development so often that it feels like “day-to-day activity” to them, even though the activities may qualify them for R&D tax credits. Even incremental improvements or discoveries may qualify as research and development activities. The research and development activities do not need to lead to a large scale breakthrough or a novel product or process.
Additive manufacturing is generally overlooked for two reasons, dependent on who is performing the work:
1) A company that prints parts for a living assumes the credit is for something bigger and more novel than day-to-day production work, regardless of the fact that they are working to solve a problem.
2) A traditional manufacturer running a printer or two alongside conventional equipment often book that work as an operations cost, regardless of whether it’s experimental work.
The real question isn’t whether they perform the work every day; instead, it’s dependent on the four-part test that is defined in IRC §41. An activity must meet all four parts of the test to qualify, regardless of what industry that activity was performed in. The four prongs are:
• Permitted Purpose: The activity must be intended to develop or improve the functionality, performance, reliability, or quality of a business component.
• Technological in Nature: The work must rely on engineering, physical or biological science, or computer science principles.
• Technical Uncertainty: The activity must be undertaken to discover information intended to eliminate uncertainty about the capability, method, or appropriate design of the business component.
• Process of Experimentation: Your team must have a process that evaluates alternatives through modeling, simulation, systematic trial and error, or other methods to eliminate uncertainty.
Activities That May Qualify for R&D Tax Credits
Material Formulation
• Developing or refining metal powders, polymer resins, or composite blends for a specific strength, weight, or durability target
• Formulating a material blend to meet a customer’s technical specification that existing materials cannot meet
Print Process and Parameter Development
• Experimenting with laser power, layer height, scan strategy, or build orientation to improve part strength, accuracy, or print speed
• Developing multi-material or multi-laser printing approaches for a new part or application
Post-Processing and Qualification
• Developing heat treatment, hot isostatic pressing, or surface finishing methods to meet a mechanical specification
• Iterating on a prototype through multiple builds or resolving a design or performance problem before commercial production
Software and Automation Activities
• Developing topology optimization or generative design software to reduce part weight or material use
• Building or customizing slicing software, simulation tools, or digital twins for a specific printer or process
• Developing robotic part handling, in-situ sensors, or AI-driven parameter tuning into a production line
What Does Not Qualify for R&D Tax Credits?
Although there are exceptions for many activities, and every activity should be reviewed by a qualified R&D tax credit professional, there are certain areas that generally will not qualify:
• Routine production printing of a part using a process that has already been qualified and is not being changed
• Quality control testing performed after a process is established
• Market research, management studies, and cost accounting, which are excluded by statute regardless of any analysis involved
• Installation of a new printer according to the manufacturer’s default settings with no material- or part-specific testing, because there is no uncertainty to resolve
Documentation Best Practices
Print logs, failed build records, and parameter test results, along with time records from engineers or technicians running trials (regardless of their job title) will all be helpful.
Though documentation is a very important piece of an R&D tax credit claim, someone who is qualified to identify activities is often qualified to find the records that are necessary to substantiate these claims; and they often don’t need to follow a rigid, scientific formula, but notes kept on qualifying activities can help substantiate a credit.
Frequently Asked Questions
Do polymer and metal printing qualify for the credit differently?
No. The four-part test applies the same way regardless of materials used. What matters is whether the work resolves genuine technical uncertainty, not whether you’re printing in plastic or titanium.
We only run one or two printers alongside traditional manufacturing equipment. Are we too small to consider the credit?
No. The credit is based on the activities, not the size of the additive manufacturing machinery you operate. A single printer used to solve a real engineering problem can generate a legitimate claim.
Does the part need to reach production, or does prototyping-only work qualify?
Prototyping can qualify on its own. Iterating on a design or process through multiple test prints, even if the part never reaches production, can still qualify.
We outsource our printing to a contract manufacturer. Can we still qualify for the credit?
Possibly, depending on who is performing the technical work and how the contract is structured. If your team is directing the experimentation, designing trials, or developing the specification being tested, it may qualify even if someone else is operating the printer. This is worth reviewing with an R&D tax credit expert since contract rules are specific and can affect the outcome.
Can we claim the credit for work on a part that ultimately failed or was abandoned?
Yes. The credit does not require the experiment to be successful. A failed print, a material that didn’t function properly, or a design that was scrapped after testing is still evidence of a process of experimentation. The four-part test does not require success.
Work with an Advisor on Additive Manufacturing R&D Credits
Companies that utilize additive manufacturing often perform work that qualifies for the R&D tax credit, and yet many haven’t claimed the credit. These companies often use additive manufacturing as one process among many. They may already have a credit study covering other parts of their manufacturing operation, but it may not capture the print engineering work specifically.
If your company is developing new products or processes using additive manufacturing, it’s worth investigating whether that work qualifies for the credit. Because these activities might be hiding in plain sight, it’s beneficial to find an expert that knows how to identify and qualify these activities so that your credit study is properly compiled.
R&D Tax Credits for Additive Manufacturing
What is Additive Manufacturing?
Additive manufacturing is more commonly known as 3D printing, and it builds a part layer by layer from a digital file, adding material where needed. Traditional manufacturing often works in a different way, cutting, drilling, or forming a part out of a large block of material to produce the final product.
The technology splits into two broad material categories:
1) Polymer printing: uses materials like plastics, resins, and composites in a wide range of applications, including rapid prototyping, dental aligners, and production parts for consumer products.
2) Metal printing: uses materials like titanium, aluminum, stainless steel, and nickel-based superalloys, generally in applications in aerospace, defense, and medical implants, where strength, weight, and precision are all concurrently important.
The companies doing this kind of work generally fall into two groups:
1) Pure-play additive manufacturing companies, such as machine builders, material developers, and print service bureaus whose entire business is printing parts for other companies.
2) Companies that use more “conventional equipment” alongside additive printing to solve a specific engineering problem such as traditional manufacturers, aerospace primes, automative OEMs, or medical device makers.
What the R&D Tax Credit is, and Why Additive Manufacturers Can Qualify
The federal research credit rewards companies for resolving genuine technical uncertainty through testing, regardless of the industry in which the uncertainty and research occurs, and no dedicated research and development department is needed in order to qualify.
Many additive manufacturing companies perform research and development so often that it feels like “day-to-day activity” to them, even though the activities may qualify them for R&D tax credits. Even incremental improvements or discoveries may qualify as research and development activities. The research and development activities do not need to lead to a large scale breakthrough or a novel product or process.
Additive manufacturing is generally overlooked for two reasons, dependent on who is performing the work:
1) A company that prints parts for a living assumes the credit is for something bigger and more novel than day-to-day production work, regardless of the fact that they are working to solve a problem.
2) A traditional manufacturer running a printer or two alongside conventional equipment often book that work as an operations cost, regardless of whether it’s experimental work.
The real question isn’t whether they perform the work every day; instead, it’s dependent on the four-part test that is defined in IRC §41. An activity must meet all four parts of the test to qualify, regardless of what industry that activity was performed in. The four prongs are:
• Permitted Purpose: The activity must be intended to develop or improve the functionality, performance, reliability, or quality of a business component.
• Technological in Nature: The work must rely on engineering, physical or biological science, or computer science principles.
• Technical Uncertainty: The activity must be undertaken to discover information intended to eliminate uncertainty about the capability, method, or appropriate design of the business component.
• Process of Experimentation: Your team must have a process that evaluates alternatives through modeling, simulation, systematic trial and error, or other methods to eliminate uncertainty.
Activities That May Qualify for R&D Tax Credits
Material Formulation
• Developing or refining metal powders, polymer resins, or composite blends for a specific strength, weight, or durability target
• Formulating a material blend to meet a customer’s technical specification that existing materials cannot meet
Print Process and Parameter Development
• Experimenting with laser power, layer height, scan strategy, or build orientation to improve part strength, accuracy, or print speed
• Developing multi-material or multi-laser printing approaches for a new part or application
Post-Processing and Qualification
• Developing heat treatment, hot isostatic pressing, or surface finishing methods to meet a mechanical specification
• Iterating on a prototype through multiple builds or resolving a design or performance problem before commercial production
Software and Automation Activities
• Developing topology optimization or generative design software to reduce part weight or material use
• Building or customizing slicing software, simulation tools, or digital twins for a specific printer or process
• Developing robotic part handling, in-situ sensors, or AI-driven parameter tuning into a production line
What Does Not Qualify for R&D Tax Credits?
Although there are exceptions for many activities, and every activity should be reviewed by a qualified R&D tax credit professional, there are certain areas that generally will not qualify:
• Routine production printing of a part using a process that has already been qualified and is not being changed
• Quality control testing performed after a process is established
• Market research, management studies, and cost accounting, which are excluded by statute regardless of any analysis involved
• Installation of a new printer according to the manufacturer’s default settings with no material- or part-specific testing, because there is no uncertainty to resolve
Documentation Best Practices
Print logs, failed build records, and parameter test results, along with time records from engineers or technicians running trials (regardless of their job title) will all be helpful.
Though documentation is a very important piece of an R&D tax credit claim, someone who is qualified to identify activities is often qualified to find the records that are necessary to substantiate these claims; and they often don’t need to follow a rigid, scientific formula, but notes kept on qualifying activities can help substantiate a credit.
Frequently Asked Questions
Do polymer and metal printing qualify for the credit differently?
No. The four-part test applies the same way regardless of materials used. What matters is whether the work resolves genuine technical uncertainty, not whether you’re printing in plastic or titanium.
We only run one or two printers alongside traditional manufacturing equipment. Are we too small to consider the credit?
No. The credit is based on the activities, not the size of the additive manufacturing machinery you operate. A single printer used to solve a real engineering problem can generate a legitimate claim.
Does the part need to reach production, or does prototyping-only work qualify?
Prototyping can qualify on its own. Iterating on a design or process through multiple test prints, even if the part never reaches production, can still qualify.
We outsource our printing to a contract manufacturer. Can we still qualify for the credit?
Possibly, depending on who is performing the technical work and how the contract is structured. If your team is directing the experimentation, designing trials, or developing the specification being tested, it may qualify even if someone else is operating the printer. This is worth reviewing with an R&D tax credit expert since contract rules are specific and can affect the outcome.
Can we claim the credit for work on a part that ultimately failed or was abandoned?
Yes. The credit does not require the experiment to be successful. A failed print, a material that didn’t function properly, or a design that was scrapped after testing is still evidence of a process of experimentation. The four-part test does not require success.
Work with an Advisor on Additive Manufacturing R&D Credits
Companies that utilize additive manufacturing often perform work that qualifies for the R&D tax credit, and yet many haven’t claimed the credit. These companies often use additive manufacturing as one process among many. They may already have a credit study covering other parts of their manufacturing operation, but it may not capture the print engineering work specifically.
If your company is developing new products or processes using additive manufacturing, it’s worth investigating whether that work qualifies for the credit. Because these activities might be hiding in plain sight, it’s beneficial to find an expert that knows how to identify and qualify these activities so that your credit study is properly compiled.
Your Project Failed. What Does That Mean For Your R&D Tax Credit?
A failed project may still qualify for the R&D tax credit. The Treasury regulations state that the ultimate success or failure does not automatically qualify or disqualify whether its development costs count as research expenditures. Before you write off a shelved prototype, a scrapped software build, or a formulation that was never launched, find out whether the work behind it qualifies.
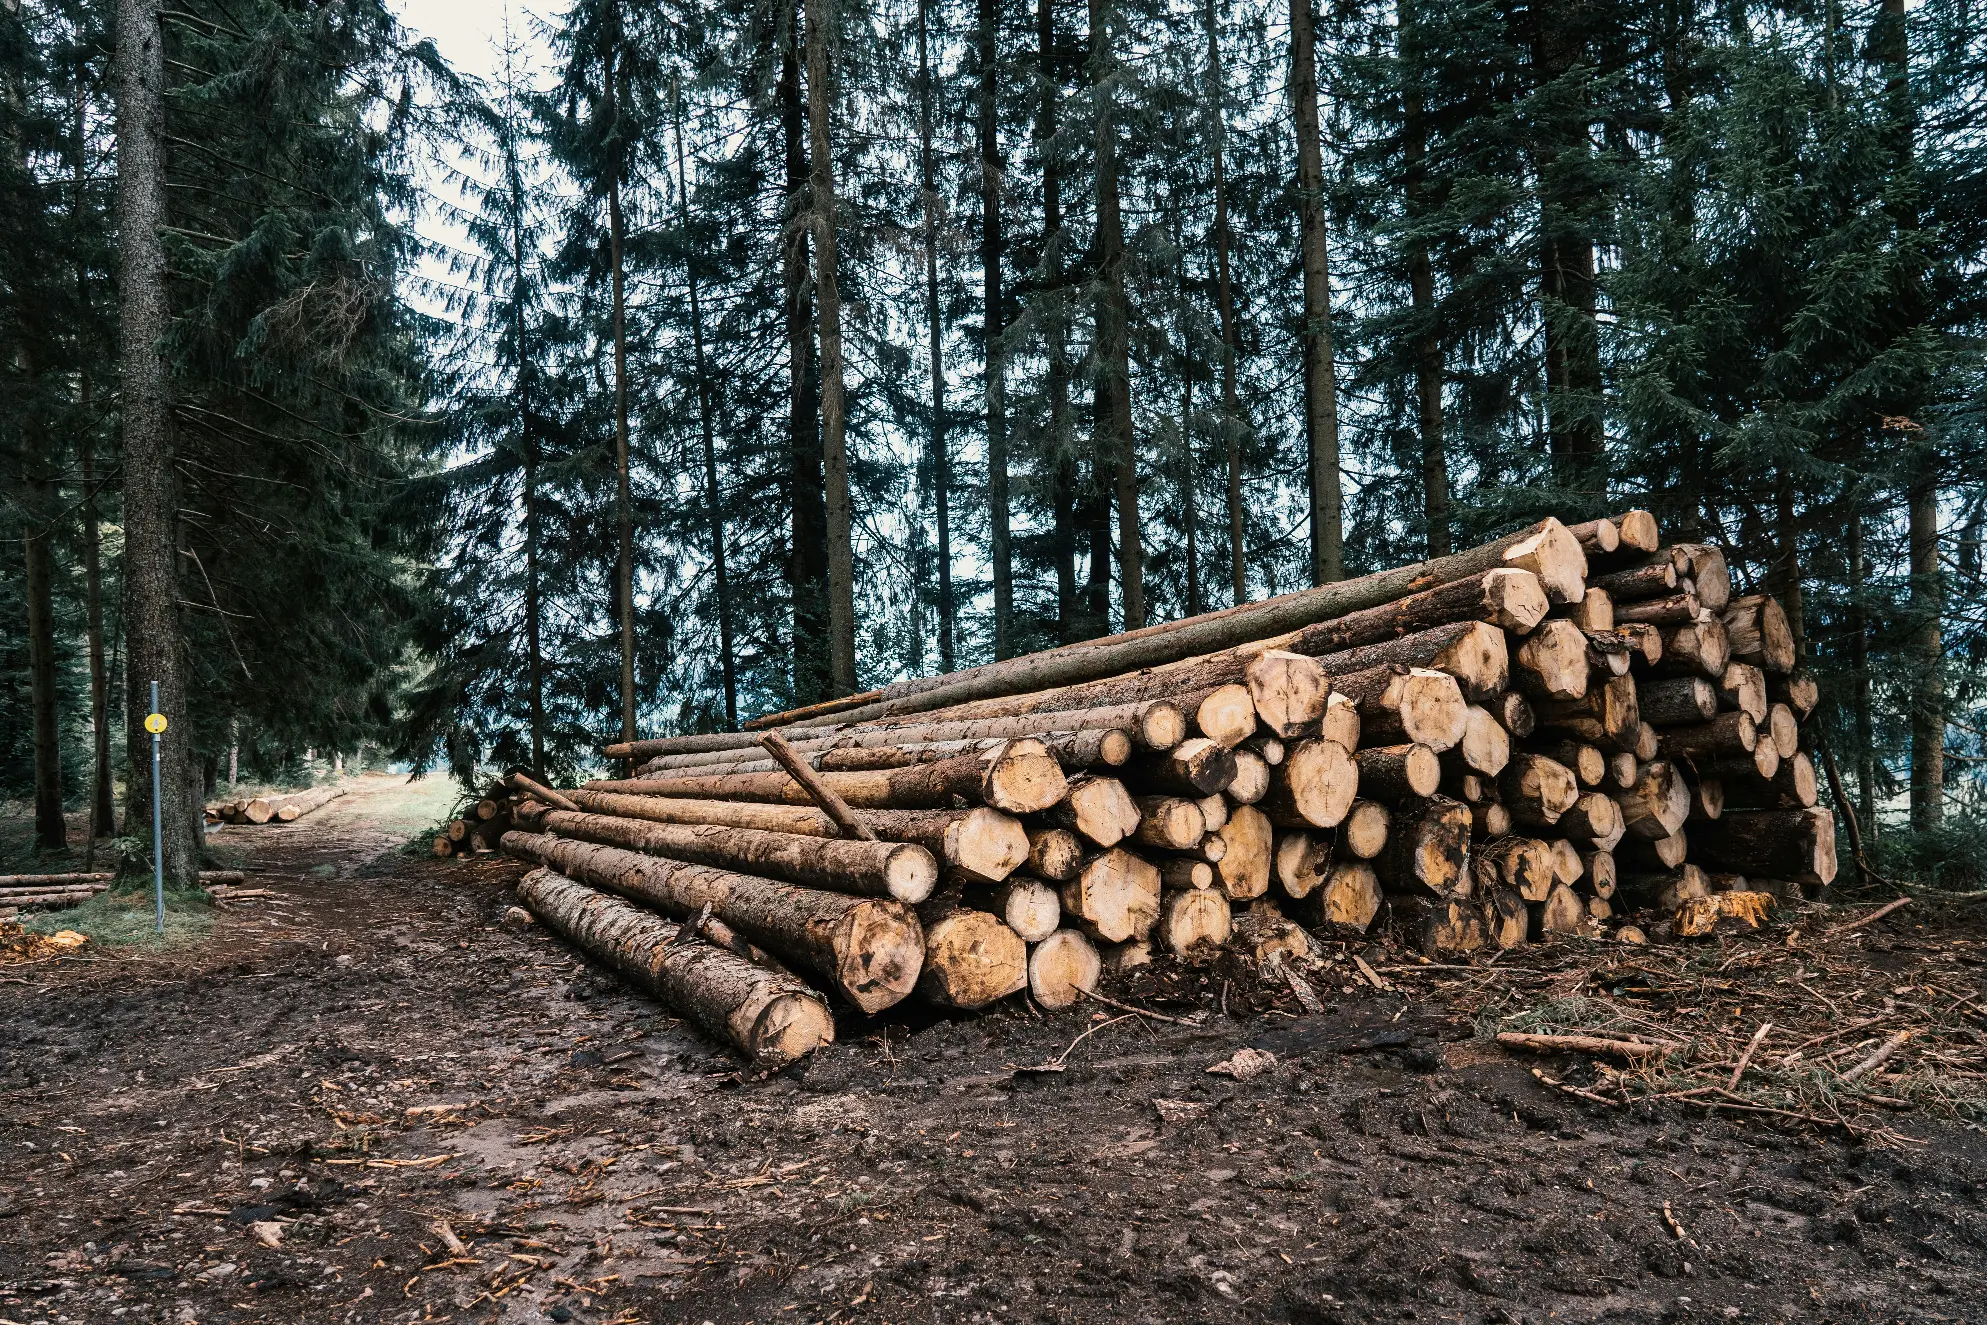
R&D Tax Credits for Timberland and Forest Management Companies
Timberland owners and forest management companies often don’t recognize that they may qualify for R&D tax credits, but many of them are already performing research and development activities when improving operations.